The best business credit cards for LLCs
Still putting business expenses on your personal card? That’s a stack of mixed-up receipts, a messier tax return and rewards you’re leaving on the table.
The right LLC credit card fixes all three. It keeps company spending separate, helps you build a credit history for your small business, and earns rewards on what you already buy. Whether you’re applying for your first business credit card for a brand-new LLC or upgrading as you grow, we compared the cards that actually deliver, including options for fair credit and for LLCs that don’t want to sign a personal guarantee.
Key takeaways
- LLCs can qualify for a wide range of business credit cards, with approval typically based on business revenue, credit history, or a personal guarantee.
- The best LLC credit card depends on your goals, whether that's cashback, travel rewards, low fees, higher limits, or expense management features.
- Using a dedicated business card helps separate personal and business finances, making bookkeeping, tax preparation, and reporting easier.
- Responsible card use can help build business credit and improve access to future financing as your company grows.
- Expense management tools like Expensify automate receipt capture, expense tracking, and reconciliation, helping LLCs get more value from every business card transaction.
The top business credit cards for LLCs in 2026
Finding the best LLC credit card means understanding which features deliver the most value for your specific situation. Whether you're researching business credit card requirements for LLC applications, looking for the best credit card for new LLC entities, or simply need a credit card for LLC expenses, these top options provide tailored solutions for different business needs.
| Card | Annual fee | Credit needed | Personal guarantee | Intro APR | Rewards | Best for |
|---|---|---|---|---|---|---|
| Chase Ink Business Unlimited® | $0 | Good to excellent | Yes | 0% on purchases for 12 months | 1.5% cash back on everything | Most new LLCs |
| Chase Ink Business Cash® | $0 | Good to excellent | Yes | 0% on purchases for 12 months | 5% / 2% / 1% cash back (bonus categories capped) | Office, internet and phone spend |
| Chase Ink Business Preferred® | $95 | Good to excellent | Yes | None | 3X points on key business categories (up to $150,000 a year) | Advertising and travel spend |
| Amex Blue Business® Plus | $0 | Good to excellent | Yes | 0% on purchases for 12 months | 2X points on the first $50,000 a year, then 1X | Points with no annual fee |
| Capital One Spark Cash Plus | $150 (offset by a $150 bonus at $150,000+ spend) | Excellent | Yes | None (charge card) | 2% cash back on everything | Established, high-spending LLCs |
| Capital One Spark Miles for Business | $0 first year, then $95 | Good to excellent | Yes | None | 2X miles on everything | LLCs that travel |
| BofA Business Advantage Unlimited Cash Rewards | $0 | Good to excellent | Yes | 0% on purchases for 7 billing cycles | 1.5% cash back (more with Preferred Rewards for Business) | Bank of America customers |
| U.S. Bank Triple Cash Rewards Visa® Business | $0 | Good to excellent | Yes | 0% on purchases and balance transfers for 12 billing cycles | 5% / 3% / 1% cash back | Service businesses |
| Capital One Spark 1% Classic | $0 | Fair or limited | Yes | None | 1% cash back on everything | Building credit |
Terms as of November 2026. Check each issuer's site before applying. Every card above requires a personal guarantee; see the EIN-only section below for options that don't.
#1. Chase Ink Business Unlimited® Credit Card
Overview: A no-annual-fee card with flat-rate cash back and a full year of 0% intro APR on purchases. Our top pick for most new LLCs.
Key features:
Unlimited 1.5% cash back on every purchase
$0 annual fee
0% intro APR on purchases for 12 months, then a variable APR
Free employee cards
Welcome offer: varies. Check Chase for the current offer.
Pros:
Simple, flat-rate rewards with no categories to track
A full year to pay off startup costs without interest
No annual fee to offset
Trade-offs:
No bonus categories for higher-spend areas
3% foreign transaction fee
Needs good to excellent personal credit and a personal guarantee
Who it’s for: New LLCs that want simple cash back and some breathing room on early expenses.
#2 Chase Ink Business Cash® Credit Card
Overview: A no-annual-fee card that pays more where small businesses spend every month: office supplies, internet and phone.
Key features:
5% cash back at office supply stores and on internet, cable and phone services, on up to $25,000 a year
2% cash back at gas stations and restaurants, on up to $25,000 a year
1% cash back on everything else
$0 annual fee
0% intro APR on purchases for 12 months, then a variable APR
Welcome offer: varies. Check Chase for the current offer.
Pros:
Some of the highest category rewards available on a no-fee card
Pairs well with the Ink Business Preferred to turn cash back into transferable points
Trade-offs:
Bonus categories are capped
Charges a foreign transaction fee
Needs good to excellent personal credit and a personal guarantee
Who it’s for: LLCs with steady spending on office supplies, internet and phone bills.
#3 Chase Ink Business Preferred® Credit Card
Overview: A low-fee points card for LLCs that spend on advertising, shipping and travel.
Key features:
3X points on the first $150,000 a year in combined purchases on travel, shipping, internet, cable and phone services, and advertising on social media and search engines
1X points on everything else
$95 annual fee
No foreign transaction fees
Welcome offer: 100,000 bonus points after you spend $8,000 in the first 3 months (as of November 2026)
Pros:
Chase Ultimate Rewards points transfer to airline and hotel partners
One of the biggest welcome offers on a card under $100 a year
Trade-offs:
No intro APR
Needs good to excellent personal credit and a personal guarantee
Who it’s for: LLCs that run ads or travel for work. Traveling abroad? See our guide to the best credit cards for international travel.
#4 The Blue Business® Plus Credit Card from American Express
Overview: A no-annual-fee points card for LLCs that spend under $50,000 a year.
Key features:
2X Membership Rewards points on the first $50,000 in purchases each year, then 1X
$0 annual fee
0% intro APR on purchases for 12 months, then a variable APR
Free employee cards
Welcome offer: 15,000 points after you spend $3,000 in the first 3 months (as of November 2026)
Pros:
Strong rewards for a no-fee card
Flexible, transferable points
Trade-offs:
The 2X rate stops at $50,000 a year
2.7% foreign transaction fee
Needs good to excellent personal credit and a personal guarantee
Who it’s for: Smaller LLCs that want points, not cash back, without paying a fee.
#5 Capital One Spark Cash Plus
Overview: A 2% cash back charge card for established LLCs with big monthly spend.
Key features:
Unlimited 2% cash back on every purchase
5% cash back on hotels and rental cars booked through Capital One Business Travel
$150 annual fee, with a $150 cash bonus every year you spend $150,000 or more
No preset spending limit
No foreign transaction fees
Welcome offer: varies. It has recently included $2,000 after $30,000 in purchases in the first 3 months, plus a second bonus for higher first-year spend.
Pros:
High flat cash back rate on everything
Normal account activity doesn’t show on your personal credit report, only late payments do
Trade-offs:
It’s a charge card, so you pay the balance in full every month
No intro APR
Needs excellent credit and a personal guarantee
Who it’s for: Established LLCs with high, steady spending.
#6 Capital One Spark Miles for Business
Overview: Flat-rate travel miles on everything, with no foreign transaction fees.
Key features:
Unlimited 2X miles on every purchase
5X miles on hotels and rental cars booked through Capital One Business Travel
Up to $120 credit for Global Entry or TSA PreCheck
$0 annual fee the first year, then $95
No foreign transaction fees
Welcome offer: varies. Check Capital One for the current offer.
Pros:
Simple earning with no categories to track
Miles transfer to airline and hotel partners
Trade-offs:
Annual fee from year two
No intro APR
Card activity reports to your personal credit report
Who it’s for: LLCs that travel and want simple, flexible miles.
#7 Bank of America Business Advantage Unlimited Cash Rewards
Overview: A no-fee flat cash back card that pays more if you bank with Bank of America.
Key features:
Unlimited 1.5% cash back on every purchase
Up to 75% more cash back through Preferred Rewards for Business
$0 annual fee
0% intro APR on purchases for the first 7 billing cycles, then a variable APR
Welcome offer: varies. Check Bank of America for the current offer.
Pros:
Simple, unlimited cash back
Strong earning for existing Bank of America business clients
Trade-offs:
The base rate isn’t competitive without the relationship bonus
3% foreign transaction fee
Shorter intro APR than the Chase and Amex cards
Who it’s for: LLCs that already bank with Bank of America, or plan to.
#8 U.S. Bank Triple Cash Rewards Visa® Business Card
Overview: A no-fee card with bonus categories built around service-business spending.
Key features:
5% cash back on prepaid hotels and car rentals booked in the U.S. Bank Travel Rewards Center
3% cash back at gas stations and EV charging stations, office supply stores, cell phone providers and restaurants
1% cash back on everything else
$0 annual fee
0% intro APR on purchases and balance transfers for 12 billing cycles, then a variable APR
$100 annual statement credit for recurring software subscriptions
Welcome offer: $750 cash back after you spend $6,000 in the first 180 days (as of November 2026)
Pros:
Uncapped bonus categories
Intro APR covers balance transfers too, which is rare
Trade-offs:
3% foreign transaction fee
Needs good to excellent credit
Who it’s for: Service-based businesses with heavy spending in the bonus categories.
#9 Capital One Spark 1% Classic
Overview: A no-fee business card built for owners with fair or limited credit.
Key features:
Unlimited 1% cash back on every purchase
5% cash back on hotels and rental cars booked through Capital One Business Travel
$0 annual fee
No foreign transaction fees
Pros:
One of the few unsecured business cards for fair credit
Responsible use can help you qualify for better cards later
Trade-offs:
No welcome offer or intro APR
High ongoing APR, so avoid carrying a balance
Card activity reports to your personal credit report
Who it’s for: LLC owners with fair or limited credit who want to build toward a rewards card.
Best business credit cards for new LLCs
Just formed your LLC? Good news: you don’t need years of business history to get approved. Here’s what a brand-new LLC needs to know.
No business credit history needed. For most small business cards, the issuer looks mainly at your personal credit and income, not your LLC’s track record. A new LLC can qualify on day one if your personal credit is in good shape.
Approval depends on your personal credit. Chase recommends a personal credit score of 670 or higher for its Ink cards. You’ll also sign a personal guarantee, which makes you personally responsible for the balance if the business can’t pay.
You may not need an EIN yet. The IRS doesn’t require a single-member LLC with no employees to have an EIN, so you can apply with your Social Security number. If your LLC has more than one member or any employees, you need an EIN. It’s free from the IRS, and most banks will ask for one before they open a business account, so it’s worth getting early.
Our picks for new LLCs:
Best overall: Chase Ink Business Unlimited. No annual fee, flat 1.5% cash back and 12 months of 0% intro APR on purchases.
Best for office and phone bills: Chase Ink Business Cash. 5% back in those categories, also with 12 months of 0% intro APR.
Best for points: Amex Blue Business Plus. 2X points with no annual fee.
Best for fair or limited credit: Capital One Spark 1% Classic.
Planning a big purchase in your first year? Compare more 0% APR business credit cards.
Business credit cards for LLCs with bad or fair credit
A lower personal credit score narrows your options, but it doesn’t close them.
Unsecured cards for fair credit
The Capital One Spark 1% Classic is built for business owners with fair or limited credit. It has no annual fee, earns 1% cash back, and doesn’t require a deposit. Pay on time and keep your balance low, and you can move up to a rewards card within a year or two.
Secured business credit cards
If your credit needs more work, a secured business card is the most reliable way in. You put down a cash deposit, which usually becomes your credit limit, and you use the card like any other. Options include the Bank of America Business Advantage Unlimited Cash Rewards Secured card and the FNBO Business Edition Secured Mastercard.
EIN-only and no personal guarantee options
Almost every bank-issued small business card, including all of the cards in our list, requires a personal guarantee and a personal credit check. True EIN-only options are mostly corporate cards from spend-management platforms. These underwrite your business’s bank balance and cash flow instead of your personal credit.
The trade-offs: you usually pay the balance in full, and the card won’t help build your personal credit. In return, your personal credit and assets stay out of it.
The Expensify Card is one example. It’s a corporate card, not a credit card, with no personal credit check, no personal guarantee and no deposit. You connect a business bank account, and spending comes out of that account.
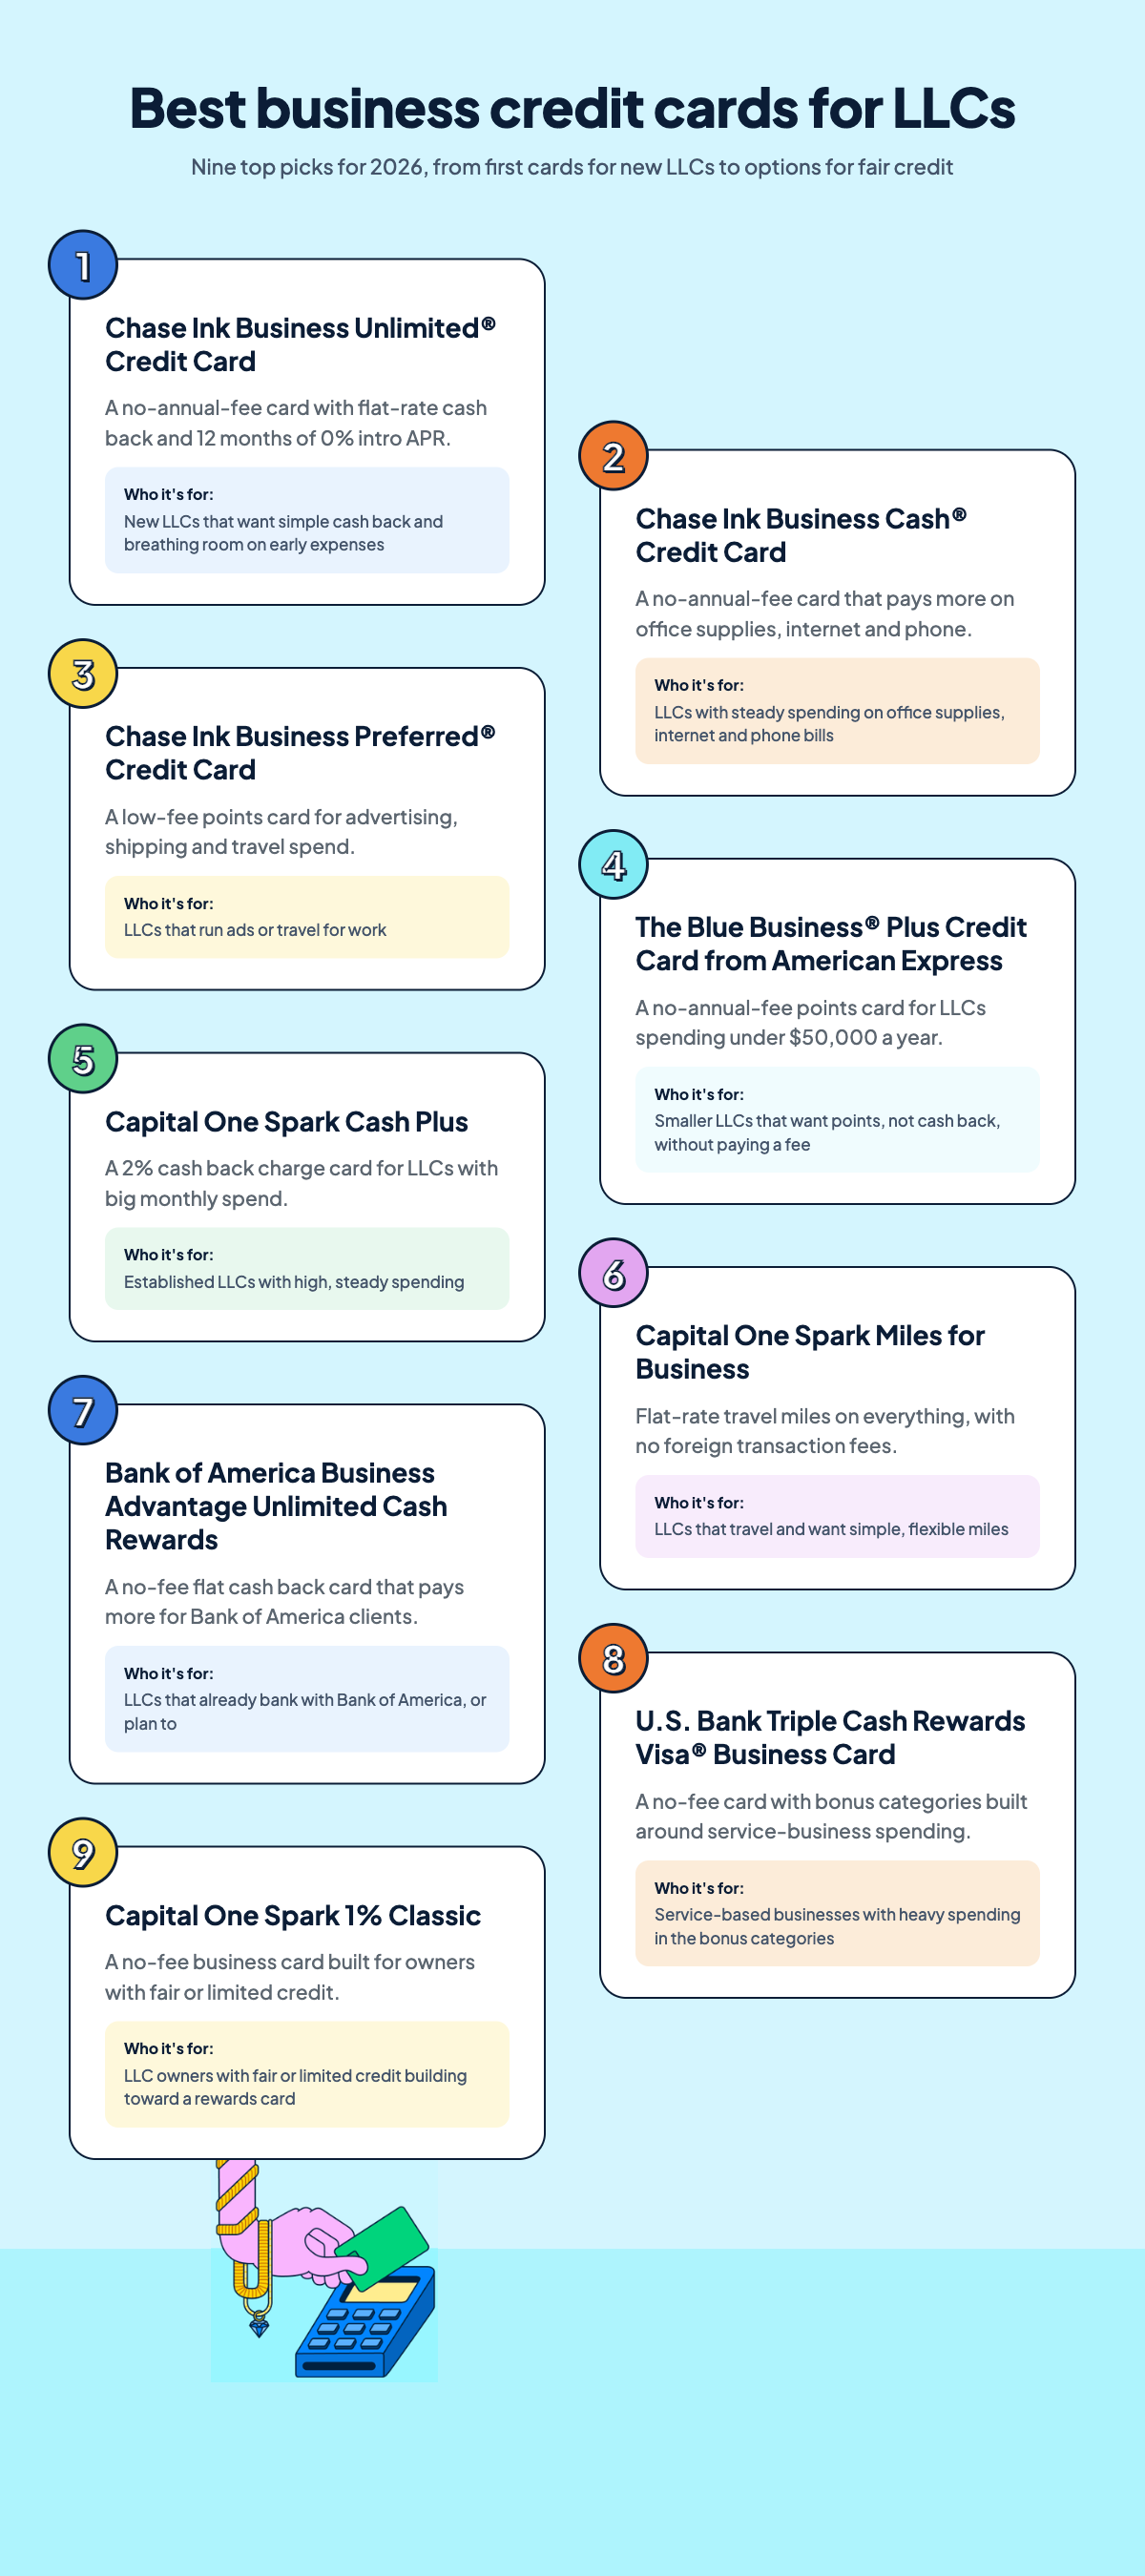
Infographic of the 9 best business credit cards for LLCs
Why your LLC needs a dedicated business credit card
Not sure if you need a business credit card for your LLC? While it’s not legally required, it’s one of the smartest moves you can make early on. A dedicated business credit card can simplify your life and support your LLC’s growth in five major ways:
Separate business and personal finances: Reinforces your limited liability and simplifies tax prep.
Build business credit: Helps establish a financial profile tied to your EIN.
Maximize deductions: Year-end summaries make sure you don’t leave money on the table.
Unlock business-specific perks: Higher limits, employee controls, and rewards tailored to how you operate.
Gain expense visibility: Track expenses in realtime and generate smarter reports.
Read more: 5 credit card hacks to maximize your business rewards (+ 5 hacks to avoid)
How to choose the best credit card for your LLC
If you're researching how to get a business card for LLC expenses, the selection process requires strategic thinking. Finding the perfect business credit card for an LLC needs doesn't happen by chance. Here's how to approach selecting the best credit card for LLC operations:
Assess your spending patterns: Review your monthly expenses. Do you spend evenly across business categories, or heavily in specific areas like travel, advertising, or office supplies? Cards with bonus categories aligned with your top spending areas will maximize your returns.
Consider your credit history requirements: Newer LLCs or those with limited credit history may need to start with cards that have less stringent approval requirements, while established businesses can qualify for premium offerings.
Evaluate reward structures: Cash back is straightforward and flexible, while points or miles systems can offer higher value when redeemed strategically, especially for businesses with significant travel expenses.
Analyze annual fees vs. benefits: A higher annual fee can be worthwhile if the card's benefits, rewards, and welcome bonus deliver value exceeding the cost. Calculate the break-even point based on your typical annual spending.
Look at additional perks: Beyond the headline rewards rate, consider benefits like purchase protection, extended warranties, travel insurance, cell phone protection, and rental car coverage.
Consider integration capabilities: Cards that seamlessly connect with your accounting software and expense management tools (like Expensify) can save hours of admin work each month.
Building business credit with your LLC credit card
For those wondering about business credit card LLC requirements, it's important to understand that a LLC credit card isn't just a payment tool. It's a powerful instrument for establishing your business's creditworthiness:
How business credit differs from personal credit
Unlike personal credit, business credit is tied to your LLC's EIN rather than your SSN. It's evaluated on different criteria and reported to specialized business credit bureaus like Dun & Bradstreet, Experian Business, and Equifax Business.
Reporting practices of different card issuers
Not every business card reports the same way. Most Capital One business cards report your activity to both business and personal credit bureaus, so your balances can affect your personal credit utilization. The Capital One Spark Cash Plus and Venture X Business are exceptions: they only show up on your personal report if you fall behind on payments. Chase and American Express generally don’t report business card activity to your personal credit report unless the account becomes delinquent. Reporting to business credit bureaus varies by issuer and can change, so if building business credit is your goal, ask the issuer before you apply.
Tips for establishing strong business credit
Make all payments on time or early
Keep your credit utilization below 30%
Maintain regular, consistent account activity
Start with cards that report to business credit bureaus
Use your card for essential business expenses, not incidental purchases
Common mistakes to avoid
Mixing personal and business expenses
Maxing out your credit limit regularly
Making minimum payments only
Applying for multiple cards in a short timeframe
Closing your oldest business credit accounts
Business credit cards vs. business charge cards for LLCs
When researching the best LLC business credit card options, you'll encounter both credit cards and charge cards. Understanding the fundamental differences between these two financial tools can help you make the right choice for your credit card LLC strategy:
| Feature | Business credit cards | Business charge cards |
|---|---|---|
| Payment terms | Can carry a balance month-to-month | Must be paid in full monthly |
| Spending limits | Fixed credit limit | No preset spending limit |
| Interest charges | Applies if balance is carried | No interest (but late fees apply) |
| Rewards | Often offer cash back or points | Typically offer premium rewards |
| Annual fees | Range from $0 to $500+ | Usually have annual fees |
| Credit score impact | Utilization affects credit score | No utilization impact on credit |
When credit cards make more sense
For business credit card for new LLC entities with uneven cash flow
When you need financing flexibility
If you want a credit card for LLC expenses with no annual fee
If you prefer straightforward rewards
When charge cards make more sense
For established businesses with consistent cash flow
When you need higher spending capacity
If you always pay balances in full
If you're focused on maximizing premium rewards and benefits
How to get a business credit card for an LLC
Getting a business credit card for your LLC takes about an hour of prep and a few minutes to apply. Here’s the process, step by step.
Get an EIN. It’s free from the IRS and takes minutes online. Single-member LLCs with no employees can apply with their Social Security number instead, but most banks want an EIN for business accounts.
Open a business bank account. It keeps LLC money separate from yours, and you’ll need it to pay the card.
Check your personal credit. Most issuers approve based on your personal score. Know where you stand before you apply.
Gather your documents. You’ll need your LLC’s legal name and address, EIN (or SSN), formation date, industry, annual revenue, number of employees, and your personal details as the guarantor.
Choose your first card. For most new LLCs, a no-annual-fee card with a 0% intro APR is the safest start. Compare 0% APR business credit cards if you’re financing a big purchase.
Apply online. Report your revenue honestly, even if it’s small. Most approvals come within minutes to a few days, and cards arrive in about 7–10 business days.
Use it to build credit. Pay on time, keep balances low, and use the card only for business expenses.
What to expect in terms of personal guarantees: Most small business credit cards require a personal guarantee, meaning you're personally liable for the debt if your LLC cannot pay. This is standard practice, even with an established LLC.
Timeline: Approval decisions often come within minutes to a few days. Once approved, most cards arrive within seven to ten business days, with some issuers offering expedited shipping options.
Managing employee spending with LLC business cards
For companies with multiple team members, having a strong LLC corporate card program offers significant advantages for expense management. Here's how to maximize your business credit card LLC benefits:
Options for issuing employee cards:
Most major issuers offer free additional employee cards
Premium cards may charge for additional cards
Some cards allow setting individual spending limits by employee
Virtual card options provide enhanced security for online purchases
Setting spending limits and controls:
Daily, weekly, or monthly spending caps
Category restrictions (limiting purchases to specific merchant types)
Geographic restrictions
Automatic approval workflows for purchases above certain thresholds
Realtime notifications for all employee card transactions
Tracking and categorizing expenses:
Automated receipt capture through mobile apps
Integration with expense management software
Automatic categorization of transactions
Digital receipt storage for audit purposes
Custom reporting by employee, department, or project
Best practices for card policies:
Create clear written guidelines for acceptable card use
Require timely submission of receipts and expense reports
Establish approval workflows for unusual expenses
Conduct regular reviews of employee spending patterns
Provide training on proper card usage and security
How to manage LLC spending (and stay tax-ready)
A business card only keeps your finances clean if what happens after the swipe is clean too. Here’s how to keep your LLC’s books audit-ready without spending your weekends on them.
Keep business and personal spending fully separate
Use your business card for business purchases only. Mixing the two makes bookkeeping harder and can weaken the liability protection your LLC gives you.
Capture every receipt the moment you get it
Snap a photo with SmartScan and Expensify reads the merchant, date and amount for you, so nothing goes missing before tax time.
Categorize as you go, not in April
Expensify codes each expense to the right business expense category automatically and syncs it with your accounting software.
Connect the cards you already have
Whichever card you choose from this list, import its transactions into Expensify and every purchase lands in your expense reports automatically. Employee cards can be added too.
Want cards without extending credit?
The Expensify Card is a corporate card, not a credit card. It draws on your connected business bank account, so there’s no personal credit check, personal guarantee or interest. Every purchase syncs instantly and matches to its receipt, and you can set limits for each employee or issue unlimited virtual cards. US cards earn 1% cash back, or 2% once your company spends over $250,000 a month (USD purchases only).
FAQs about LLC credit cards
-
Not legally, but it’s highly recommended. It separates personal and business expenses, preserves liability protection, simplifies taxes, and helps build business credit.
-
Apply online using your LLC’s legal name, EIN, and financial details. Be ready to provide personal info as a guarantor. It’s a standard part of the process.
-
No. Sole proprietors and other entities qualify too. But having an LLC strengthens your application and helps build separate business credit.
-
You can, but you shouldn’t. It complicates accounting, muddies your tax records, and can blur the line between personal and business finances, which could undermine your LLC’s liability protection in certain legal situations. Having a dedicated LLC credit card is a smarter move.
-
Cards like the Ink Business Unlimited and Capital One Spark Classic are known for easier approvals and solid starter benefits.
-
LLCs don’t have a credit score at formation. You build it over time by opening accounts, using credit responsibly, and making on-time payments.
-
Not always. The IRS doesn’t require a single-member LLC with no employees to have an EIN, and many card applications let you apply with your Social Security number instead. Multi-member LLCs and LLCs with employees need one. An EIN is free from the IRS and most banks require one for business accounts, so it’s worth getting.
-
Almost all small business credit cards do. A personal guarantee makes you personally responsible for the balance if your LLC can’t pay. Cards without one are mostly corporate cards that underwrite your business’s finances rather than your personal credit.
-
Yes, with the right card. Business cards built for fair credit, like the Capital One Spark 1% Classic, are an option. If your credit needs more work, a secured business card, backed by a cash deposit, is the most reliable way to get approved and start rebuilding.